Every certificate re-performed. Every cycle. Across the whole book.
For regional banks, bank ABL divisions and asset-based lending teams. CORA works from the borrower's own aging and inventory, applies the agreement deal by deal, and puts the breaks in front of your team before the advance.
At a glance
From gross, not as reported
The calculation starts from gross collateral, never from the eligible figures on the borrower's certificate.
Held to the agreement
Ineligibles, caps, concentrations and reserves applied as the agreement writes them, deal by deal.
Exact to the cent
Each break is sized exactly, never rounded, so the review starts from the real number.
In detail
No certificate goes unchecked.
A borrowing base is re-performed each time it is reported, so your team reviews the breaks rather than rebuilding the math.
- Recomputed from gross
- Breaks named against the borrower's certificate
- Reviewed before the advance
Third-party work lands on the record.
Appraisal values apply from their as-of date. Field exam reserves take effect through your confirmation, one by one, so the collateral picture stays current to the latest work.
- Appraisal values from their as-of date
- Field exam reserves through the lender's confirmation
- Each reserve traced to its source
Your tiers, your signatures.
Advances and decisions run on your own approval tiers, with named people at each seat and a signing sheet that records who approved what and when.
- Your own approval tiers
- A signing sheet for each decision
- Approvals on the audit trail
How lenders use it.
Work the receivables
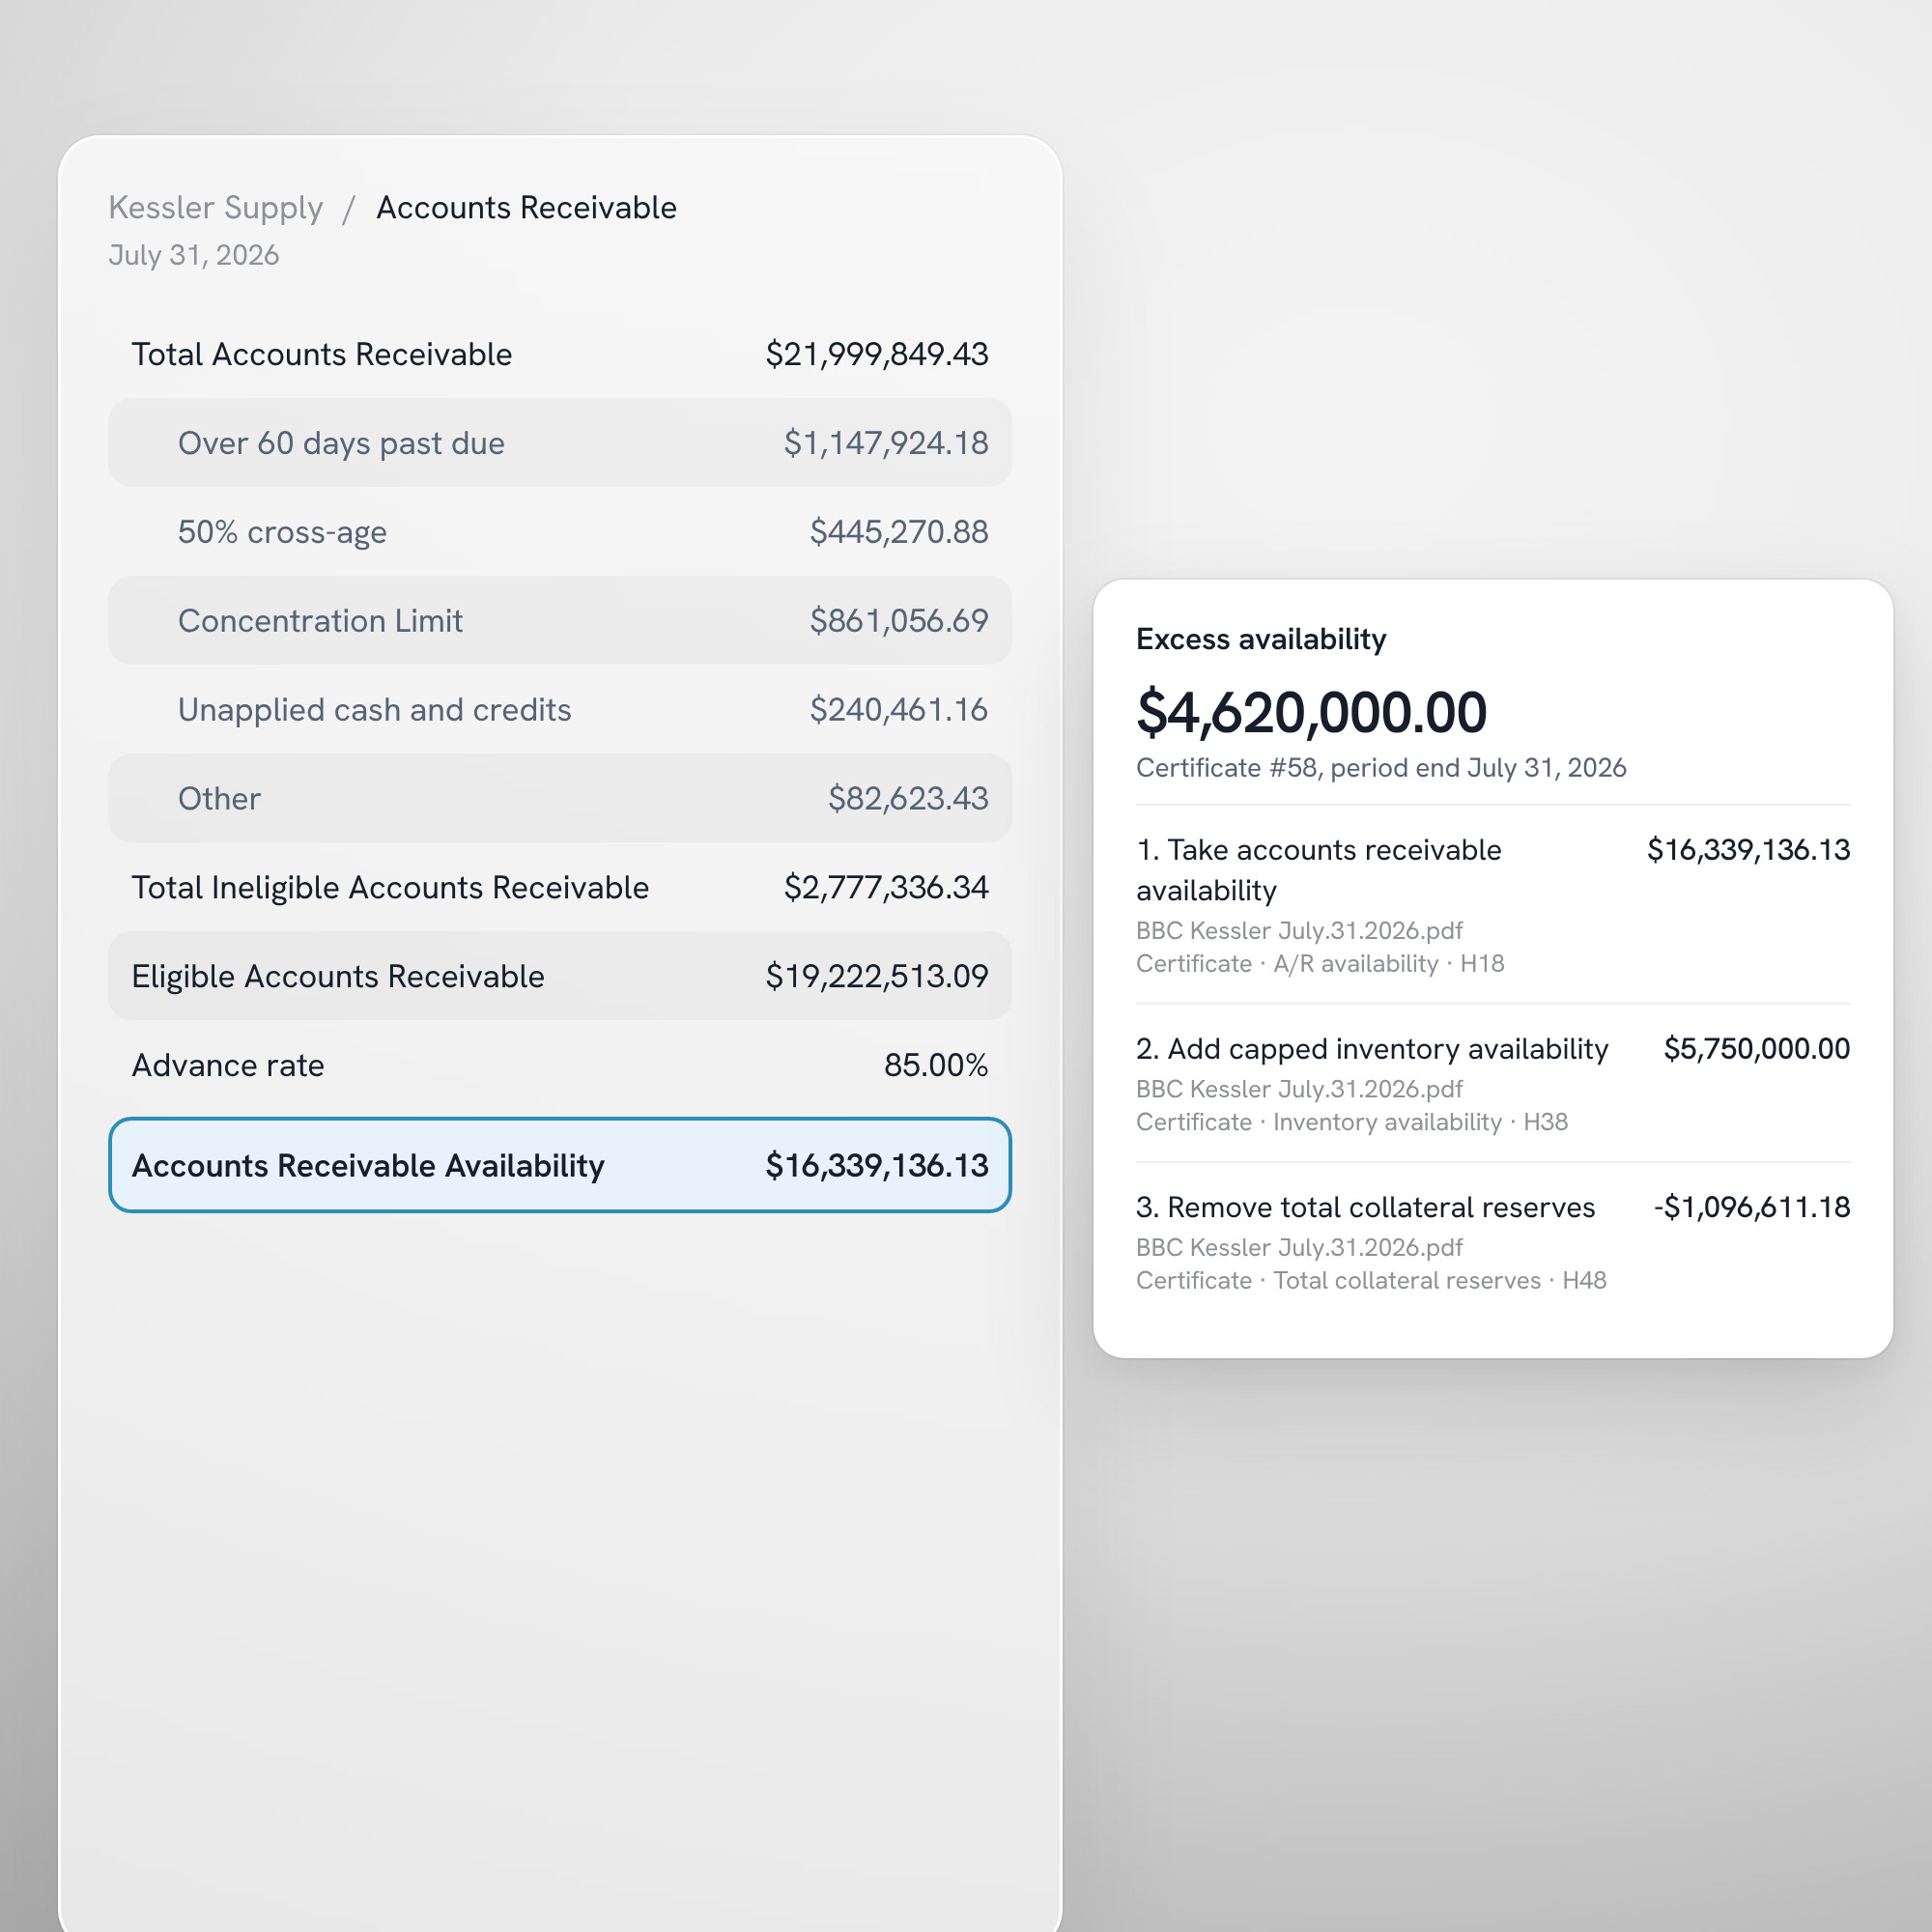
Start from gross receivables and take out each ineligible as the agreement writes it.
Size the availability
Arrive at eligible receivables and their availability, held exact to the cent.
Trace excess availability
Follow excess availability step by step, each step traced to its source on the borrower's certificate.
Questions.
Does CORA rely on the borrower's eligible figures?
No. It recomputes the borrowing base from gross, starting with the borrower's own aging and inventory, and applies the agreement's ineligibles, caps, concentrations and reserves itself.
What happens when our number differs from the borrower's certificate?
The difference is named as a break, sized to the cent, before the advance.
How do appraisals and field exams reach the borrowing base?
Appraisal values apply from their as-of date. Field exam reserves take effect only as your team confirms them, one by one.
Can CORA follow our credit approval policy?
Yes. Advances and decisions run on your own approval tiers with named seats, and the signing sheet records who approved what and when.
Are covenants covered as well?
Yes. Covenants are tested at their dates, and springing terms are watched until they apply.
How is the bank's data protected?
It is encrypted in transit and at rest, behind SSO, MFA and role-based permissions, in a shared cloud environment or one dedicated to your institution. SOC 2 Type I is complete, and Type II is in progress with an independent auditor.
See your book re-performed.
Bring one of your certificates and watch CORA run it from the borrower's own files.